September 10, 2026
AEROSPACE & DEFENSE CONFERENCE HIGHLIGHTS
What is the Gabelli A&D Conference?
The Gabelli Aerospace and Defense Conference was held September 9-10 in New York City, bringing together asset managers, investors and industry leaders to examine the forces reshaping the aerospace and defense sectors. Around 115 people attended the September 9 “Defending Our Nation” Leadership Forum, while the September 10 32nd Annual Aerospace & Defense Symposium welcomed more than 130 attendees in person and 120 virtually. The conference provided an opportunity to engage with leading companies and industry participants across the aerospace and defense sectors.
What were the defining themes?
The two-day conference focused on the sector’s defining themes, including space, autonomy, artificial intelligence, cyber, rising global defense spending, sustained commercial aviation demand, aftermarket opportunities and technological modernization. The commercial aerospace presenters reaffirmed our view that the commercial aerospace market will return to a healthy state over the long-term. The discussions also highlighted the continued importance of technological innovation and evolving defense requirements across the industry.
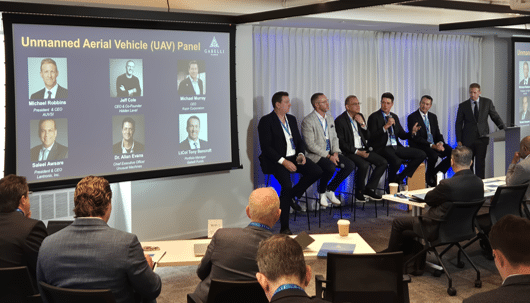
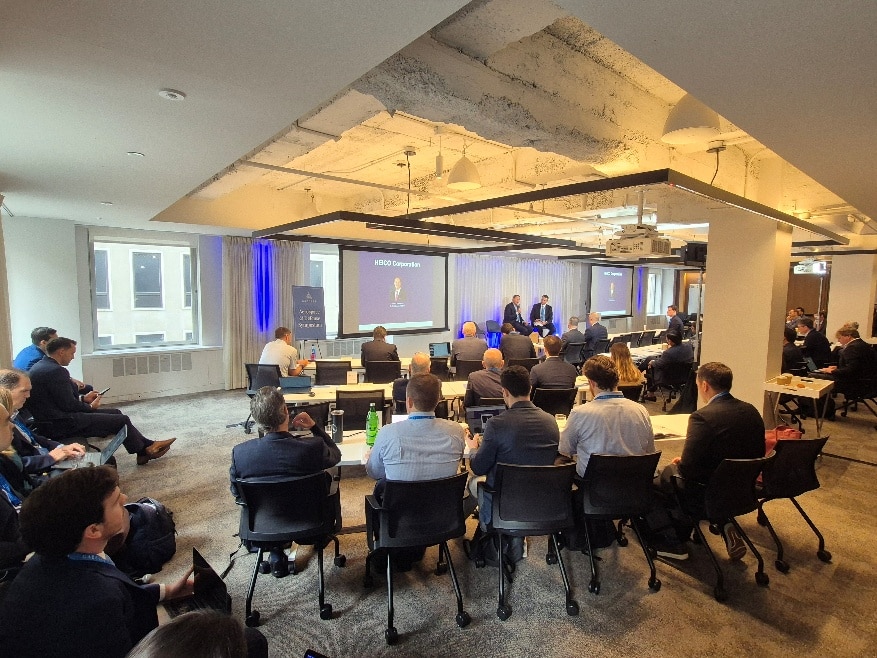
| Exhibit 1 Unmanned Aerial Vehicle (UAV) Panel | Exhibit 2 Fireside Chat HEICO Corporation | ||
 |
 |
||
| Source: Gabelli Funds | Source: Gabelli Funds |
INTRODUCTION: COMMERCIAL AEROSPACE
What is the civil aircraft demand outlook?
Boeing and Airbus forecasts (2026 CMO/GMF) project demand for approximately 43,500-43,700 new passenger and freighter aircraft through 2045, with the global fleet nearly doubling to ~50,000 aircraft. Large carriers continue placing significant orders (e.g., Airbus’s strong May 2026 intake of 379 gross orders, including major A220 and A320neo deals) to secure delivery slots often extending into the 2030s. Fleet modernization remains a priority amid strong long-term passenger traffic growth projections of ~3.6% annually (RPKs).
What is the civil aircraft supply outlook?
The industry remains demand-unconstrained, with the core challenge being OEM production ramp-up and on-schedule deliveries. Airbus and Boeing maintain massive backlogs (Airbus >9,300; Boeing ~6,700+), providing multi-year visibility. Recent monthly delivery records (e.g., strong summer 2026 figures) show progress, but consistent execution at higher rates (e.g., Airbus targeting 75 A320-family/month, Boeing scaling MAX and widebodies) is key to unlocking operating leverage.
Can supply chains keep up with the airframers?
Normalization toward pre-pandemic (2019) levels is underway, but persistent bottlenecks in engines, specialty alloys, and certain systems continue to constrain monthly output and limit the pace of production increases. Supply chain resilience, diversification, and scalability are major themes at the 32nd annual Gabelli A&D Symposium 2026. Over the next 1-2 years, further stabilization is expected to support higher, more efficient build rates and act as a tailwind – though near-term pressures remain evident in delivery pacing.
What is the outlook for the aftermarket?
Strong growth is projected, with the aircraft aftermarket parts/MRO segment expected to expand at a high-single-digit CAGR (roughly 6-8% in various forecasts) through the early 2030s, driven by rising revenue passenger miles (returning to long-term above-GDP trends), fleet expansion/renewal, and sustained high utilization. Travel demand has proven resilient. Boeing’s Services Market Outlook underscores a multi-trillion-dollar opportunity in support services over the period.
INTRODUCTION: U.S. AND EUROPEAN DEFENSE
What is the outlook for U.S. defense?
In 2025, U.S. defense spending grew from $874 billion to $901 billion, an increase of $27 billion or about 3.1% year over year. Further, NATO members excluding the United States spent approximately $607 billion in 2025, which represents an 18% increase from $516 billion in 2024. Given the developing geopolitical risks, the elevated international defense-spending environment should persist. An area of key growth as it relates to defense procurement is within missiles and missile defense.
What is a focus for U.S. defense spending?
One high-profile U.S. initiative is the proposed Golden Dome missile defense program, a multilayered shield intended to detect and intercept advanced missile threats using a combination of ground-, sea-, and space-based sensors and interceptors; the administration has outlined an initial price tag of around $185 billion with early funding included in recent budget proposals, and the effort reflects broader emphasis on next-generation air and missile defense capabilities amid rising strategic competition.
Where did Europe stand before the NATO summit?
European NATO members’ defense expenditure in the ten years before the invasion of Ukraine stood at around 1.5% on average as a share of GDP. At the time, NATO members were expected to allocate at least 2% of their GDP to defense. That compares to circa 3.5% in the U.S., and 2.5% for NATO total, including the U.S. and Canada. NATO Europe, after the invasion of Ukraine in 2022, already substantially increased defense expenditure to about 2.0% as a share of GDP. Overall, we estimate the European NATO members’ core defense expenditure in 2024 to be around $485 billion.
What is the outlook for European defense?
In June of 2025, the NATO summit took place in The Hague, Netherlands. At this event, NATO members committed to a new set of spending and capability targets. NATO members made the commitment to invest 3.5% as a share of GDP by 2035 to resource core defense requirements and to meet the NATO capability targets. We estimate NATO Europe core expenditure to reach around 2.6% as a share of GDP, or $690 billion by 2027 and 3.0% or $900 billion by 2030. A key driver of this absolute growth with more than 25% is Germany.
908 Devices (MASS – $11.18 – NASDAQ) A&D Symposium Highlights
COMPANY OVERVIEW
908 Devices Inc. develops and commercializes purpose-built handheld devices for chemical analysis. The company’s products employ mass spectrometry, optical spectroscopy, and related technologies to provide point-of-need detection and identification for public safety, defense, and security applications, supported by software, training, and expert reach-back services.
REASON FOR COMMENT
The following are key takeaways from 908 Devices’ CEO and co-founder Dr. Kevin Knopp, and CFO Joe Griffith, at our 32nd Annual Aerospace & Defense Symposium:
How has your recent performance been? Over the past 18 months the company has transformed into a business focused entirely on handheld chemical detection at the intersection of public safety and national security, serving a mission set running from the local firehouse and patrol officer to federal agencies and the warfighter, with the cost structure rebuilt around that focus. Second quarter 2026 results showed revenue growth of 23% to $16.1 million, recurring revenue at approximately 31% of mix, trailing-twelve-month revenue of roughly $61 million, adjusted gross margin of 57%, and an adjusted EBITDA loss reduced to under $2 million, a 50% year-over-year improvement, with $101.5 million in cash and no debt.
What are some macro tailwinds? Management identified tailwinds described as the most powerful and durable of a career. Most notably, the illicit drug crisis has broadened beyond fentanyl to nitazenes and related compounds, with global cocaine seizures up 68% over four years, and fentanyl’s designation as a weapon of mass destruction in December opening new funding streams while reframing illicit synthetics as a national security threat.
What is the differentiation beyond hardware? Management argued the company is not selling hardware alone. Alongside the device portfolio sit 24/7/365 expert reach-back providing on-site decision support, best-practice scenario training built around customers’ actual workflows rather than a manual, and an expanding Team Leader application for usage tracking, fleet management, AI-powered guidance, and enterprise reporting.
What are opportunities with the NIRLab acquisition? NIRLab, acquired in May, pairs near-infrared spectroscopy hardware with a cloud-connected software platform and a proven subscription model, with more than 100 active customers globally, over a million analyses performed, and roughly 50% of revenue from recurring sources with high annual retention. Integration is following the playbook used successfully with RedWave, and within the first 60 days the U.S. commercial team engaged more than 30 agencies and hundreds of prospects.
What are some programs of record? Within CBRN defense, the MX908 supports four mission sets on a single device, including fourth-generation A-series agents engineered by their developers with explicit knowledge of fielded NATO detection systems, pharmaceutical-based agents that conventional detectors do not recognize in aerosol form, explosives and IED exploitation, and integration as a node in sensor networks including growing UGV and UAV platform deployments. The device is embedded in programs of record: selection in 2019 to power the AVCAD next-generation chemical detector with Smiths Detection as prime, a $25 million multi-year Army EOD award in 2021, Milestone C and initial production of 122 AVCAD systems in 2023, and a $10 million Air Force award the same year. Management noted AVCAD’s current contract has run its course with the next phase unawarded, and that AVCAD is excluded from 2026 guidance, making any win upside.
Albany International (AIN – $60.22 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Albany International Corp. is a developer and manufacturer of engineered components. It is engaged in advanced textiles and materials processing, specializing in designing and manufacturing high-performance engineered fabrics and composite components and assemblies that serve industries, such as paper, industrial manufacturing, and aerospace. Its Machine Clothing segment is a producer of custom-designed fabrics and high-speed process belts critical in the manufacture of all grades of paper products characterized primarily as paper machine clothing. The segment supplies highly engineered consumable, permeable, and impermeable belts. Its Albany Engineered Composites segment provides composite technology solutions and is a manufacturer of engineered components, structures and assemblies for aerospace and defense applications. The segment provides highly engineered, advanced composite structures and assembly solutions to customers and platforms in the commercial and defense markets.
REASON FOR COMMENT
The following are key takeaways from AIN’s CEO Gunnar Kleveland, at our 32nd Annual Aerospace & Defense Symposium:
How does the Machine Clothing segment fit in the business? Albany is built on a single foundation of material science, and specifically weaving, with well over 100 years of experience. Machine Clothing produces the engineered belts and felts that run paper machines, removing 99% of the water while retaining 1% of the fiber, and at close to 50% gross margin with strong cash generation management described it as the company’s bank, funding the aerospace build-out.
What was the resolution with the strategic review? In October 2025, Albany announced an approximately $147 million loss reserve adjustment on the CH-53K program, driven by greater-than-planned labor content and higher material input costs, with other contracts at the site also performing poorly. The review was run as a dual path rather than a sale process, and Albany negotiated out of an unfavorable Gulfstream life-of-program contract and secured a contract extension with Boeing for one-piece composite fuselage frames on the 787.
What is the opportunity with LEAP? Three sites are moving to 24/7 operations to follow the CFM ramp, and Albany is now matching Safran’s consumption of blades and fan cases after correcting a period of overproduction. The contract is cost-plus, which cushioned the trough but limits growth relative to the customer as costs decline, though management sees potential to convert it to a conventional contract over time. Albany is approaching 250,000 cumulative blades and expects to produce as many as 40,000 fan blades next year.
What are your next-generation platforms? Airbus has stated its next-generation wing will be composite and out-of-autoclave and has publicly named Albany as a capability partner; management indicated the wing work would be significantly larger than LEAP, focused on spars, braces, and stiffening structure, and would require investment in the U.K. or the U.S. Albany is working with Safran on the open rotor, covering both blade and stator, and has demonstrated ducted-fan capability, with final material and technology decisions expected in 12 to 18 months.
What does your missile portfolio look like? JASSM and LRASM are in backlog with requests to double, triple, and quadruple output, and Albany has been selected for LRSO wings. The larger opportunity sits outside backlog in ceramic matrix composites, where Lockheed Martin selected Albany for a hypersonic missile because near-net-shape weaving combined with carbonization, graphitization, and densification roughly halves cost and compresses timelines. Management has progressively revised this opportunity from mid-term to near-term, with solid rocket motors now the largest prize given the absence of a supply chain capable of meeting Department of War demand, and discussions underway with both primes and neo-primes.
Astronics (ATRO – $69.70 – NASDAQ) A&D Symposium Highlights
COMPANY OVERVIEW
Astronics Corporation, headquartered in East Aurora, NY, is a provider of advanced technologies to the global aerospace, defense, and electronics industries. Its products and services include advanced electrical power generation, distribution and motion systems, lighting and safety systems, avionics products, systems and certification, aircraft structures and automated test systems. The company operates through two segments: Aerospace and Test Systems. The Aerospace segment designs and manufactures products for the global aerospace industry. Its product lines include lighting and safety systems, electrical power generation, distribution and seat motion systems, aircraft structures, avionics products, systems certification, and other products. The Test Systems segment designs, develops, manufactures and maintains automated test systems that support the aerospace and defense, communications and mass transit industries as well as training and simulation devices for both commercial and military applications.
REASON FOR COMMENT
The following are key takeaways from Astronics’ CEO Peter Gundermann, and CFO Nancy Hedges, at our 32nd Annual Aerospace & Defense Symposium:
What is your portfolio concentration? Astronics is roughly a $1 billion company reporting in two segments, Aerospace at about 90% of sales and Test Systems at about 10%. Approximately 70% of total company revenue is commercial aerospace, with business jet and military each contributing about 10%. In-flight entertainment and connectivity is the single largest product concentration at roughly half of the entire company, where Astronics holds very high market share in several critical components. Management’s thesis is secular: passengers increasingly expect to be entertained, connected, and powered at all times, including in flight.
What is the MV-75 opportunity? Astronics is supplying the entire electrical distribution system on the Army’s MV-75 as a subcontractor to Bell, spanning generators through end-use systems. Management is directing investors to model roughly $1 million per shipset on a preliminary basis, with a lengthy negotiation still ahead. The system carries high content because the Army specified a single architecture capable of handling all foreseen missions rather than mission-optimized variants, which reduces cost efficiency but preserves flexibility.
What are your current growth drivers? Seat motion is the fastest-growing product line, with actuators and motion-control devices for high-end seating roughly doubling in 2026 to approximately $100 million, aided by the October 2025 acquisition of Buhler, as airlines redesign cabins around lie-flat seats and moving dividers; management expects a further 30-35% increase in 2027. Margin levers include portfolio simplification, workforce efficiency as churn has settled and rejects have fallen, the turnover of legacy contracts lacking inflation protection, and above all volume.
What are your aftermarket economics? Of the roughly 70% of sales that are commercial transport, the split is approximately 50/50 between line fit and aftermarket, but margins are the same in both channels because IFEC products are sold to airlines and integrators such as Panasonic and Thales rather than to the airframers. Cabin interiors are reworked every five to eight years and entertainment systems are typically replaced at that point as consumer device capability advances, generating repeat sales on the same airframe.
What are the opportunities within Test Systems? After four to five difficult years, Test Systems has returned to a modest operating profit, though margins remain held back by mix and under-absorption at current volumes, and the approximately $215 million, five-year U.S. Army and U.S. Marine Corps Radio Test Program covering 28 radio families is entering high-volume production and should lift segment margins toward aerospace levels, with NATO foreign sales as potential upside. Management acknowledged investors buy Astronics as an aerospace company and said fixing Test Systems provides the flexibility to decide its long-term role.
Crane Company (CR – $202.87 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Crane Company is an industrial manufacturing and technology company. The company is a manufacturer of engineered components for mission-critical applications focused on the aerospace, defense, space and process flow industry end markets. Its segments include Aerospace & Advanced Technologies and Process Flow Technologies. The Aerospace & Advanced Technologies segment supplies critical components and systems, including original equipment and aftermarket parts, primarily for the commercial aerospace, and the military aerospace, defense and space markets. The Process Flow Technologies segment is a provider of engineered fluid handling equipment for critical applications. The segment is composed of Process Valves and Related Products, Pumps and Systems and Commercial Valves. The company also designs and manufactures multi-stage lubrication pumps and lubrication system components technology for critical aerospace and defense applications.
REASON FOR COMMENT
The following are key takeaways from Crane’s CEO Alex Alcala, and SVP of Aerospace Jay Higgs, at our 32nd Annual Aerospace & Defense Symposium:
What is the Crane Business System? Crane is a roughly $3 billion global business organized around two strategic growth platforms, and management’s organizing framework is the Crane Business System, developed over more than two decades, which drives a consistent cadence of innovation and productivity and is scalable to support accelerated inorganic growth. Asked what differentiates the system when most industrial companies maintain one, management argued the substance matters less than the execution, citing a process-driven culture, cadence, discipline, and results that are never considered sufficient.
How are you competitively positioned? The Aerospace & Advanced Technologies segment is expected to deliver nearly $1.4 billion in 2026, with over 90% sole-sourced and 100% proprietary products and no build-to-print content. Mix is roughly 60% commercial aerospace, 30% military and defense, and 10% non-aerospace industrial, with a 70/30 OEM to aftermarket split.
What are the biggest growth drivers? Management characterized growth as broad-based rather than program-concentrated, noting Crane roughly doubled content on the new narrowbodies versus prior generation aircraft, so Boeing’s rate recovery and Airbus rate increases flow through directly, with commercial aftermarket growing well into double digits. On defense, the F-16 brake control upgrade program contributes roughly $30 million annually of incremental growth, while AESA radar power conversion represents a larger opportunity in an area where Crane historically had no presence, with each program carrying nine-figure lifetime value.
What is your nuclear positioning within PFT? Process Flow Technologies has delivered 1,200 basis points of margin improvement since 2017 through repositioning into higher-growth markets. Nuclear now exceeds 10% of the segment following the Reuter-Stokes acquisition, which added radiation sensing to a core of valves and services. The end market environment has inverted, with plants that were being decommissioned three or four years ago now receiving 50-year license extensions and investment, producing mid-single-digit growth today. New construction represents the upside, with strong positions on the AP1000 and on small modular reactors, none of which was contemplated in the acquisition model.
What is your M&A appetite? Crane closed two acquisitions on January 1, 2026, adding four businesses: Druck, Panametrics, Reuter-Stokes, and optek-Danulat, with integration described as off to an incredible start and the outlook already exceeding expectations. Process Flow historically maintained two M&A platforms in process valves and rotating pump equipment; a third platform in measurement and instrumentation has been added, materially expanding the funnel, while Aerospace remains the highest priority target space.
Ducommun (DCO – $166.45 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Ducommun Incorporated provides value-added manufacturing solutions to customers in the aerospace, defense and industrial markets. It specializes in two core areas – Electronic Systems and Structural Systems – to produce complex products and components for commercial aircraft platforms, mission-critical military and space programs, and sophisticated industrial applications. Electronic Systems designs, engineers and manufactures high-reliability electronic and electromechanical products used in worldwide technology-driven markets, including aerospace and defense and industrial end-use markets. Electronic Systems product offerings primarily range from prototype development to complex assemblies. Structural Systems designs, engineers and manufactures large, complex contoured aerostructure components and assemblies and supplies composite and metal bonded structures and assemblies. Structural Systems products are primarily used on commercial aircraft, military fixed-wing aircraft, and others.
REASON FOR COMMENT
The following are key takeaways from Ducommun’s CEO Steve Oswald, at our 32nd Annual Aerospace & Defense Symposium:
How has the company transformed? Ducommun is the oldest company still active in California, founded as a general store in 1849, and supplied the tubular aluminum for the Spirit of St. Louis. Oswald has served as CEO for just over nine years, arriving as the first outside hire into the role when the company was in poor condition. The central transformation metric is the shift away from contract manufacturing, which represented 91% of the business on arrival; engineered products is now approximately 25% and aftermarket has grown from 6% in 2017 to a projected 15% by the end of next year.
What is your opportunity with missiles? Missile revenue grew 68% in the quarter, and missiles, radar, and electronic warfare together represent more than 20% of sales. Ducommun supplies components on a largely sole-source basis for Tomahawk, where it produces 18 harness types, as well as SM-3, SM-6, and AMRAAM, primarily on the electronic side, with RTX at roughly 30% of revenue. Critically, very little of this is reflected in the profit and loss statement yet, as the seven-year agreements covering Lockheed’s PAC-3 and THAAD and Raytheon’s Tomahawk order are still ahead.
What is the growth opportunity with radar? Growth in radar and electronic warfare is driven by OEM offloading: Ducommun assumed complex, high-mix, low-volume circuit card work from Raytheon’s Massachusetts facilities for the SPY-6 radar, now produced in Tulsa, OK, and followed a similar path on Next Generation Jammer into Appleton, Wisconsin. Management described the internal dynamics candidly, noting supply chain organizations want the savings while operations resist losing control, so customers never transfer all work initially and trust builds over four or five years.
What are you seeing with commercial recovery? Destocking, driven largely by the legacy Boeing Wichita fuselage situation, has been the two-year headwind and is expected to conclude by year end. Ducommun is shipping at a mid-30s pull rate for the MAX, and management praised a recent Boeing visit, describing a factory floor focused on quality with energy markedly different from three or four years ago. Management noted the company generated over $100 million with the MAX in 2019 at rate 57, then $25 million the following year, while holding EBITDA percentages through the disruption; if rates reach 63 on the MAX and 14 on the 787, substantial operating leverage would follow without requiring a new facility.
What are your financial targets? The Vision 2027 targets established in December 2022 are essentially being met, with revenue on track and EBITDA margins moving from 13% toward the 18% goal, currently at 17.1% and expected to reach the target by the end of 2027.
Elbit Systems (ESLT – $744.75 – NASDAQ) A&D Symposium Highlights
COMPANY OVERVIEW
Elbit Systems, headquartered in Haifa, Israel, ranks among the top 25 defense contractors globally. Its sales are primarily to governmental entities and prime contractors under defense and homeland security programs. In 2025, Elbit generated approximately 30% of its sales in Israel, 25% in Europe, 20% in the Americas, and 20% in APAC and the rest of the world.
The offerings include systems and products for military vehicles, artillery and mortar systems, protection systems, and munitions across land, air and sea applications (Land segment, 36% of FY-25 EBIT adj); systems and products for airborne platforms (Aerospace, 21%); a wide range of electronic warfare solutions (ISTAR and EW, 18%); Elbit’s U.S. business (ESA, 17%); and command, control, communications, computers, intelligence, surveillance, and reconnaissance systems (C4I and Cyber, 8%).
REASON FOR COMMENT
The following are our key takeaways from our fireside chat with Elbit Systems CFO Dr. Yaacov (Kobi) Kagan at the 32nd Annual Aerospace & Defense Symposium:
What are your mid-term targets? Elbit Systems does not provide formal mid-term revenue guidance. That said, Elbit has an internal target of achieving mid-teens sales growth in 2027, in line with its target for 2026 and following 14-16% growth in 2024 and 2025. This growth is expected to be supported by strong market demand and effective sales conversion. Elbit has achieved an annual margin expansion of almost one percentage point since 2022. Elbit expects this trend to continue, supported by a stronger pipeline and improved backlog profitability as well as operating leverage.
What was your most recent guidance? Elbit Systems targets mid-teens revenue growth for 2026, following roughly 16% y/y growth in H1-26. For margins, the company guides to an EBIT adj margin of 10% or slightly above, following 10.3% in the first half (H1-25: 8.8%). In terms of investments, the capex target for 2026 is 3% of sales, or $300m, up from $225m in 2025.
What is your update on laser-based drone/ missile defense? A ground-based anti-drone defense system has already been deployed. Elbit is also under contract to develop a solution for Israeli Air Force helicopters and fighter jets. The helicopter solution should be operational in the short term. Elbit comments that the solutions should become a sales growth engine and have attracted significant interest from potential customers around the world at recent trade shows.
What are your capital allocation priorities? Elbit prioritizes organic growth through investments in R&D and capex. The company is also looking for M&A opportunities from both regional and technological perspectives. Elbit has already completed three bolt-on acquisitions in H1-26, including U-TacS (a U.K.-based UAV company) and Bluewhite (an Israeli developer of autonomous ground solutions). Europe is a key region, with Germany being a particular focus.
HawkEye (HAWK – $15.97 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
HawkEye 360 Inc. is a radio frequency data analytics company that owns and operates a constellation of commercial satellites flying in formation to detect, characterize, and geolocate radio frequency signals. The company delivers signal intelligence products and analytics to defense, intelligence, and national security customers worldwide, with applications spanning maritime domain awareness, spectrum monitoring, and early warning.
REASON FOR COMMENT
The following are key takeaways from HawkEye 360’s CEO John Serafini, at our 32nd Annual Aerospace & Defense Symposium:
What are your capabilities? HawkEye 360 owns and operates a constellation of more than 30 satellites flying in clusters of three, the first commercial formation flight in the private sector, at roughly 550 kilometers in low earth orbit. Equipped with software-defined radios and antennas, the system detects essentially any signal above one watt between 30 MHz and 18 GHz, geolocates to under a kilometer, and converts the result into an actionable intelligence product.
What is your differentiation with proprietary data? Management resisted comparison to other space companies, arguing HawkEye is focused on effects rather than imagery. The differentiator is proprietary data: outside the classified environment, HawkEye is the only holder of billions of radio frequency data points collected over a decade with its own constellation, data the frontier artificial intelligence laboratories cannot access. Products range from raw IQ data delivered into sophisticated customers’ own signal processing architectures to fully turnkey analytics delivered with low latency, since day-old targeting data has limited value.
What is your recent financial performance? Revenue was $117.7 million in 2025, up 74% year over year, or approximately $177 million pro forma including Innovative Signal Analysis (ISA), acquired in December 2025, with current-year guidance of $215-220 million that management expressed confidence in following a strong second quarter. International revenue grew 134% year over year and now represents roughly 43% of the business.
What is your total addressable market? Management illustrated capability at three levels: tactical, monitoring a known DPRK missile site every 35 to 45 minutes and flagging deviations from baseline such as surges in radio traffic; operational, tracking mobile surveillance and target acquisition radars tied to surface-to-air missiles across Eastern Europe and helping distinguish real systems from decoys; and strategic, having tracked a three-month Chinese buildup ahead of the June 2020 Galwan Valley confrontation. The overall signals intelligence market was sized at approximately $25 billion, of which the space-based portion is roughly a third at $7-8 billion and is growing fastest at a projected 18% annually.
What are some constraints you are seeing? Block 3 satellites strip roughly 75% of spacecraft cost by narrowing the mission, at 15 kilograms versus 35 with fewer antennas and one fewer software-defined radio; clusters 15 and 16 launch within weeks, with the first Block 3 at the end of this year or early next. Block 4 introduces a larger 100-120 kilogram bus capable of both international and classified missions, collectively doubling the constellation to roughly 60 satellites and reducing global revisit from 35 to 45 minutes down to 10 minutes. Latency is targeted below 10 minutes through ground station densification from 12 today toward 16 to 18, greater onboard processing, and eventually optical crosslinks.
HEICO (HEI – $307.77 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
HEICO Corporation is a manufacturer of jet engine and aircraft component replacement parts. Its segments include Flight Support Group (FSG) and Electronic Technologies Group (ETG). The FSG segment consists of HEICO Aerospace Holdings Corp. and HEICO Flight Support Corp. and their subsidiaries. FSG uses technology to design and manufacture jet engine and aircraft component replacement parts. FSG repairs, overhauls and distributes jet engine and aircraft components, avionics and instruments for domestic and foreign commercial air carriers and aircraft repair companies, as well as military and business aircraft operators. The ETG segment consists of HEICO Electronic Technologies Corp. and its subsidiaries. ETG designs, manufactures and sells various types of electronic, data and microwave, and electro-optical products, including infrared simulation and test equipment. It also designs and manufactures avionics controls, including navigation, audio, surveillance, and communication panels.
REASON FOR COMMENT
The following are key takeaways from HEICO’s Co-CEO Victor Mendelson, at our 32nd Annual Aerospace & Defense Symposium:
What is your operating philosophy? Since the Mendelson family took control in 1990 through a proxy contest, when HEICO was a $26 million business, the organizing principle has been cash flow above all else, without commitment to any particular operating paradigm. The best-known business designs, manufactures, and sells jet engine and aircraft replacement parts in competition with OEMs, a model management repeatedly compared to generic drugs challenging a de facto monopoly. From that base HEICO added accessory component repair and overhaul, then distribution and specialty manufacturing.
What is the current demand environment? Management reported record backlogs and record orders across the board and pushed back firmly on the view that commercial aviation is about to roll over, noting that orders are very strong, parts remain short, and forecast retirement rates may not materialize given travel demand. Defense is perhaps stronger still, with committed backlogs and continuing resolutions serving as the bridge, though management noted the midterm elections are unlikely to be a positive event based on current polling. Non-aerospace end markets are extremely strong, much of it data-center driven, with customers demanding faster turn times.
What is the current PMA runway & market ceiling? Defense is now roughly 30% of sales with Flight Support Group defense organic growth in the upper 20s, but management expects mix to remain in roughly the same range excluding acquisitions because commercial aviation grows at 1.5-2.0x GDP and the parts business grows at 1.5-2.0x that. HEICO adds approximately 500 PMAs per year, though the internal focus is revenue per PMA rather than count, with the split running roughly 80–90% PMA versus DER repairs. The company generally does not target more than about 10% of a given market; the overall PMA market is under 2% of aftermarket spend and HEICO holds the substantial majority of it.
How has Wencor been integrating? Since closing in August 2023, the $2 billion Wencor acquisition has produced capability swaps between plants, joint go-to-market activity, and data sharing, but the most consequential change is incorporating more Wencor PMA parts into HEICO’s repair and overhaul work, which has lifted R&O margins. HEICO is deliberately deemphasizing lower-margin, less critical repairs in favor of those where its own PMA content can be embedded.
What do your margins look like? Flight Support Group operating margins are in the low-to-mid 20s with cash margins approaching 30% once more than 300 basis points of amortization is added back, and management described EBITDA as a flawed metric given ongoing capital expenditure requirements, preferring EBITA and cash. ETG has been guided to 26–28% EBITDA, and management is holding to that range despite stronger recent quarters.
Hexcel Corporation (HXL – $85.98 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Hexcel Corporation develops, manufactures, and markets lightweight, high-performance structural materials, including carbon fibers, specialty reinforcements, prepregs, honeycomb, matrix systems, adhesives, and engineered composite structures. The company’s products are used in commercial aerospace, space and defense, and industrial applications. The company has two reportable segments: Composite Materials and Engineered Products
REASON FOR COMMENT
The following are key takeaways from Hexcel’s CFO Jamie Coogan, at our 32nd Annual Aerospace & Defense Symposium:
How are you vertically Integrated? Hexcel is the only U.S.-domiciled, vertically integrated manufacturer of carbon fiber composite materials, taking raw chemical inputs and producing carbon fiber, prepreg, honeycomb core, and engineered parts. End markets span commercial aerospace, regional and business jets, defense, space including launchers and satellites, and nascent eVTOL and drone applications. Management emphasized that the business extends well beyond fuselage and wing structure, with propulsion representing a substantial portion, where composite fan blades and cases paired with honeycomb core enable designs that metallic solutions cannot support.
What is your fixed cost absorption? The asset base was constructed to support 2019 peak build rates, leaving Hexcel under-absorbed on fixed costs for an extended period, so the commercial recovery flows through an installed asset base rather than requiring new investment. In 2019, the company generated roughly $2.35 billion of revenue at approximately 13% EBIT margins, against roughly $1.9 billion in 2025. Returning commercial to prior peak build rates represents approximately $500 million of incremental revenue, with a further approximately $200 million available from defense and space.
What is the current A350 Visibility? Management acknowledged the industry was repeatedly misled on the timing of build rate recovery, with the back half of 2025 disappointing relative to expectations, but characterized 2026 as different. Hexcel now runs a triangulation process on the A350, combining inbound purchase orders, customer skyline information, and cross-checks against the sub-tier suppliers it feeds to confirm consistent signals, giving confidence around guidance of approximately 80 aircraft this year with indications 2027 could move higher.
What is your content ceiling? Narrowbody aircraft are roughly 15% composite today, a large portion of that in propulsion, versus approximately 50% for widebodies. Whether the next-generation single aisle adopts a composite fuselage remains undecided, though management believes a composite wing represents the minimum case and works with Boeing and Airbus research teams on material selection. Certain architectures, including blended wing body designs, can only be executed in composites. The principal technical question is producibility rather than capability, specifically ensuring composite materials can be manufactured at the rates platforms require.
What are your defense & space costs? The CH-53K carries shipset value of roughly $2.5–3.5 million, combining honeycomb core and prepreg with engineered structural components, and Hexcel also produces the rotor blades, a program that carries forward into Black Hawk and generates annuity revenue at OEM-like margins well after peak build rates pass. In space, management expects composites to prevail as reuse economics dominate, since fatigue and maintenance costs of metallic solutions offset the cost of prepreg, while in the interim additional launch activity drives demand for rocket motors, launch vehicles, and satellites.
Moog (MOG’A – $367.83 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Moog Inc. is a designer, manufacturer, and systems integrator of high-performance precision motion and fluid controls and control systems. The company’s high-performance systems control military and commercial aircraft, satellites, and space vehicles, launch vehicles, defense systems, missiles, automated industrial machinery, marine, and medical equipment. Its segments include Space and Defense, Military Aircraft, Commercial Aircraft and Industrial. The company also specializes in designing and manufacturing ruggedized fiber optic transceivers and assemblies used in major aerospace and defense programs across both United States and international markets. These mission-critical components deliver high-bandwidth speeds with compact signal density, enabling enhanced digitalization solutions across space, air, land and sea domains.
REASON FOR COMMENT
The following are key takeaways from Moog’s CEO Pat Roche, and CFO Jennifer Walter, at our 32nd Annual Aerospace & Defense Symposium:
How has your company evolved? Moog began in 1951 with a single product used to steer a surface-to-air missile, and the trajectory extended through ICBMs and launch vehicles including Gemini, Saturn, and most recently Artemis. The company spans precision components through extensively engineered systems of systems, including all primary and secondary flight controls on the 787 and A350 and the triple-redundant flight control computer on the Embraer E2.
What is the margin simplification process? The June 2023 investor day committed to 100 basis points of average annual margin improvement, delivered over three years using pricing and simplification, and management was explicit that these levers are not exhausted. Simplification examples include closing a Radford motor facility into Murphy, North Carolina, selling a Czech motor business given existing Italian capability, and consolidating three U.S. slip-ring operations into a single 100,000 square foot building.
What is your capacity readiness for missile demand? Missile sales exceed a quarter of a billion dollars, having compounded at over 20%, and critically none of the anticipated three to five times step-ups are reflected in backlog, which is entirely at current rates. Moog participates on nearly all twelve missiles on the Pentagon’s priority munitions list, including PAC-3, THAAD, Tomahawk, AMRAAM, SM-3, and SM-6, with negotiations running 18 to 24 months and scenario analysis on facilities and supply chain already complete.
What are your segment economics? In military aircraft, aftermarket is approximately 25% of segment revenue, Joint Strike Fighter production is steady, and MV-75 is in a three-year EMD phase past its development peak contributing over $100 million of development revenue, with low-rate initial production anticipated at the end of the decade and full rate in the 2030s, at which point it would exceed JSF in importance. Commercial aircraft carries structurally lower margins for three reasons: tariffs of roughly 200 basis points versus minimal exposure in military, commercial aftermarket pricing meaningfully above OE unlike in military, and the current OE ramp reducing aftermarket as a share of segment revenue from about 33% toward 30%.
What are your current capital projects? The Advanced Integrated Manufacturing Center at East Aurora was opened on August 14, comprising 150,000 square feet. The new facility places six machining centers in sequence with a robot on a track handling loading and unloading, with in-process testing within the cell and cells organized by capability; where 300 machinists staff the current center, the new site anticipates roughly 85 higher-skilled personnel. Two-thirds of equipment is installed with approximately 200 products already transferred, and roughly 1,500 products in total will migrate through October 2027.
Oceaneering (OII – $46.11 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Oceaneering International, Inc. provides engineered services and products and robotic solutions, primarily to the offshore energy, defense, aerospace, and manufacturing industries. The company operates through five operating segments: Subsea Robotics; Manufactured Products; Offshore Projects Group; Integrity Management & Digital Solutions; and Aerospace and Defense Technologies.
REASON FOR COMMENT
The following are key takeaways from Oceaneering’s CEO Rod Larson, at our 32nd Annual Aerospace & Defense Symposium:
How are you positioned? Management opened by addressing why an energy company was presenting at a defense conference, highlighting the dual-use applications of its hybrid vehicles. Oceaneering is a global technology company providing solutions in high-consequence environments, backed by 60 years of subsea experience and focused on robotics, software, and automation. Aerospace and Defense Technologies represents 15 to 20% of the business, running at the upper end of that range in the first half of 2026 versus 17% last year. The remaining 80 to 85% of the company is derived from energy.
What is the Aerospace & Defense Technologies composition? ADTech comprises two components. Oceaneering Technologies performs the advanced work including ROVs, AUVs, subsea habitats, and management of the West Coast submarine rescue system for the U.S. Navy. Marine Services provides fleet readiness with SUBSAFE certification, including hull repair, sail repair, and torpedo launch repair when nuclear submarines arrive for refueling, drydock work for Virginia and Columbia class vessels, and now manufacturing of hatch assemblies and components for new-build submarines.
What is the defense opportunity? Management framed the opportunity as a confluence of two trends. On one side are large exquisite assets, specifically maintaining nuclear submarine availability through faster drydock throughput, additional capacity, and raising build rates from 1.8 per year to at least three, with further demand if AUKUS proceeds, sized loosely as long-lead items for close to two dozen builds across an eight-year window.
Do you have any recent contracts of note? Oceaneering was awarded prime contractor status by the Department of Defense on the Maritime Mobility System, the largest contract in company history on either side of the business. The company did not quantify the size of this award; for reference, the last disclosable award was $550 million. Management explained that the content was familiar and the company had been a subcontractor on larger projects and prime on smaller ones, but here its unique capabilities were the most critical element, so it elected to lead. Preparation began two and a half to three years before bid submission, including hiring experts who had been consumers of similar products and engaging former primes as subcontractors.
What is your growth model? The company projects the ADTech business can account for 30% of the total company over the next three to five years just based on organic growth alone. The model assumes energy growth of 3 to 5% through the cycle and defense at a 15% compound annual growth rate, which management conceded others might view as conservative. Management rejected the characterization of a strategic pivot, stating this has always been the strategy and that the world has changed around the company. On acquisitions, management does not anticipate a headline transaction at high revenue or EBITDA multiples, noting the company does not need to buy credibility, and prefers bolt-on acquisitions of niche technologies from known subcontractors.
RENK (R3NK – €41.30 – XETR) A&D Symposium Highlights
COMPANY OVERVIEW
RENK, headquartered in Augsburg, Germany, ranks among Europe’s top ten defense contractors by market cap. Of RENK’s defense revenues (FY-25: around 74%), about half are generated from European NATO members, and its civil sales (26%) stem from marine and other industrial applications. Germany is the largest customer, accounting for more than €150m in sales.
The defense offerings include drivetrain components and suspensions for tracked and wheeled military vehicles, along with aftermarket services (Vehicle Mobility Solutions segment, around 72% of FY-25 EBIT adjusted); drivetrain components for naval vessels (Marine & Industry, 18%); and naval slide bearings (Slide Bearings, 10%).
REASON FOR COMMENT
The following are our key takeaways from our fireside chat with RENK CEO Dr. Alexander Sagel at the 32nd Annual Aerospace & Defense Symposium:
What are your mid-term targets? RENK targets 2030 organic sales of €2.8-3.2bn (FY-25: €1.37bn), implying a FY 25-30% sales CAGR of 17% at the midpoint. In addition, RENK guides to up to €1.0bn via M&A. The margin target is “above” 20% (FY-25: 16.9%), implying an EBIT adj of more than €600m (consensus €641m, i.e., roughly in line). The defense share is expected to reach 90% (FY-25:74%). With its new strategy, RENK targets aftermarket sales of €1bn by 2030 (FY-25: €490m, i.e., a 36% share) and €2bn in the years thereafter. For the Vehicle Mobility Solutions segment, RENK indicates an EBIT adj margin potential of 25% (FY-25: 20.4%) once plant capacity is fully utilized.
What was your most recent guidance? RENK guides 2026 sales of “more than” €1.5bn and the “upper half” of its EBIT adj guidance range of €255-285m (consensus: €275m, i.e., roughly in line). RENK also expects around €2bn in orders. For the Vehicle Mobility Solutions segment, RENK guides EBIT adj margins to above 21% and “does not exclude the option” to reach 22% or higher (consensus: 21.4%).
Are you on track to achieve your implied H2 guidance? The 2026 guidance implies more than €860m in sales in the second half, after around €640m in the first half. The second half also factors in €80-100m of higher margin sales to Israel from Germany, after very limited sales in the first half. In terms of orders, RENK guides to €300-400m in both Q3 and Q4 after €1.2bn in the first half. The pipeline would be very diversified across both domains and regions. Achieving guidance would also not be dependent on recording orders related to the German Arminius Boxer armored vehicle or the F-127 frigate programs.
What are your ambitions on M&A? Following the acquisition of David Brown Defence (closing targeted for Q4-26), RENK is looking for further market consolidation, with a focus on the Naval and aftermarket business. The industrial business within the Marine & Industry segment would not be for sale, despite not being a core business for RENK.
Rheinmetall (RHM – €995.80 – XETR) A&D Symposium Highlights
COMPANY OVERVIEW
Rheinmetall, headquartered in Düsseldorf, Germany, is Europe’s second largest defense contractor by market cap and ranks fifth by FY-25 defense sales. Rheinmetall generates most of its revenue from European NATO members. Germany is the largest customer, accounting for an estimated more than €3.5bn in sales.
The offering includes new armored tracked vehicles, wheeled tactical and logistics vehicles, and related maintenance (Vehicle Systems segment, estimated 25% of FY-26 EBIT adjusted); weapon systems and artillery and tank ammunition (Weapon and Ammunition, 55%); air defense systems and defense electronics (Electronic Solutions, 15%); and from 2026 new surface vessels and their maintenance (Naval, 5%).
REASON FOR COMMENT
The following are our key takeaways from our fireside chat with Rheinmetall Head of Investor Relations Dirk Winkels at the 32nd Annual Aerospace & Defense Symposium:
What are your mid-term targets? Rheinmetall targets 2030 sales of €50bn (FY-25: €9.9bn) of which roughly €45bn are organic, translating into a FY 25-30 sales CAGR of around 35%. At the midpoint, the segment guide implies a 2030 EBIT adj of €9.6bn (FY-25: €1.84bn), 9% above consensus of €8.80bn. Of the five segments, Weapon and Ammunition is the most relevant, with midpoint guidance of €4.5bn, or roughly 45% of group EBIT adj. Rheinmetall expects the cancelled F-126 frigate program to account for less than 3% of its 2030 outlook. Nevertheless, the company expects to offset the cancellation through national and international programs. Rheinmetall therefore reiterates its Naval segment 2030 outlook of €5bn in sales (FY-26: €1.0-1.2bn) and a margin of more than 15%.
What was your most recent guidance? Rheinmetall guides FY-26 sales of €13.7-14.2bn, with organic growth of 28-31%, and midpoint EBIT adjusted of €2.65bn (consensus: €2.68bn, i.e., 1% lower). Rheinmetall also expects backlog to reach €100-120bn by year-end (H1-26: €80.5bn; Q4-25: €64bn), which we estimate implies roughly €30-50bn of H2-26 orders (FY-25 orders: €26.5bn).
What is your update on the Arminius order? Project Arminius is the German military’s designation for its large-scale Boxer armored vehicle program and represents Rheinmetall’s largest opportunity in its current contract pipeline. Management expects a decision on the future of the Arminius program in September (€12.5bn fixed order, €26bn frame contract, €2bn service). The related parliamentary decision is expected on 9 December.
What is your update on the portfolio? Rheinmetall announced on 3 June the sale of its civilian Power Systems business (FY-25: sales €1.9bn, EBIT adjusted €57m) to Munich-based industrial group AEQUITA for a purchase price of €350m. Closing is expected in Q4-26. Following the cancellation of the F-126 frigate, Rheinmetall intends to pause the evaluation of a potential acquisition of German Naval Yards until there is greater visibility into the Naval order pipeline.
TAT Technologies (TATT – $38.05 – NASDAQ) A&D Symposium Highlights
COMPANY OVERVIEW
TAT Technologies Ltd. provides a range of services and products to the commercial and military aerospace and ground defense sectors through its Kiryat Gat facility in Israel, and through its subsidiary in the United States, Limco-Piedmont Inc. (Limco-Piedmont), which it operates through Limco Airepair Inc. (Limco). It operates in four segments: original equipment manufacturing (OEM) of heat transfer products and aviation accessories components, which it operates through its Kiryat Gat facility; heat transfer services and products, which it operates through its Limco subsidiary; maintenance, repair and overhaul (MRO) services for aviation components, mainly APUs and landing gear, which operates through its Piedmont Aviation Component Services LLC (Piedmont) subsidiary, and overhaul and coating of jet engine components, which operates through its subsidiary, Turbochrome Ltd.
REASON FOR COMMENT
The following are key takeaways from TAT’s CEO Igal Zamir, at our 32nd Annual Aerospace & Defense Symposium:
How has the company transformed? TAT operates four units plus a trading and leasing arm: thermal components, where it performs Tier 1 OEM production for Boeing, Embraer, and Textron and is a leading MRO provider serving roughly 300 customers; auxiliary power units as a Honeywell-licensed shop; landing gear focused on regional jets, ATRs, Embraer, and Gulfstream; and jet engine component overhaul and coating through Turbochrome. Management emphasized the transformation rather than the product list: TAT is more than 50 years old but used COVID to restructure, streamline product lines, and reset strategy, and has averaged over 20% year-over-year growth since the second quarter of 2022, entirely organic.
What is your backlog visibility? Backlog stands at a record $615 million, up from roughly $180-200 million three and a half years ago, which management treats as approximately four years of coverage. Entering 2026, roughly 60% of the year’s revenue was already covered by long-term agreements, with roughly 40% of annual revenue coming from non-contractual customers and proving very steady; the 2027 pipeline already exceeds the 60% coverage threshold the company targets.
What is the Honeywell opportunity? Honeywell holds roughly 80% of the global APU market, and in 2019 changed strategy such that authorized shops receive parts while others pay full catalog price. TAT chose to remain Honeywell-authorized while many competitors went independent on the assumption they could acquire engines for teardown; COVID broke that model, with teardown assets disappearing and APUs that sold for $400-500 thousand pre-COVID now trading at $2.4-2.5 million according to management.
What is your M&A strategy? Management framed acquisitions two ways: strategically, bringing a broader package of products to airlines TAT has already penetrated shifts the conversation from price toward total value and addresses the vendor-count problem airlines face; financially, TAT trades at roughly 18-20x EBITDA while others in the industry transact at 10-13x. The target range is companies with $50-150 million of revenue, implying deal values of roughly $75-250 million, with smaller transactions funded from the existing credit facility and free cash flow and larger ones requiring additional equity.
What is your capacity with landing gear? Organic capital expenditure is essentially maintenance only, as TAT invested heavily during COVID and runs one shift, so it could double sales with existing facilities by adding people; the one constraint is floor space at the North Carolina APU shop, where engines on the floor have grown from 10–15 to more than 100. Landing gear is the least attractive line at roughly 5% of the business, with critical forgings still unavailable on waits of up to two and a half years, minimal PMA, and no acceptable substitution.
Textron (TXT – $77.88 – NYSE) A&D Symposium Highlights
COMPANY OVERVIEW
Textron Inc. is a multi-industry company that leverages its global network of aircraft, defense, industrial and finance businesses to provide customers with various solutions and services. The company’s segments include Textron Aviation, Bell, Textron Systems, Industrial, and Finance. The Textron Aviation segment manufactures, sells and services Cessna and Beechcraft aircraft, and services the Hawker brand of business jets. The Bell segment supplies military and commercial helicopters, tiltrotor aircraft, and related spare parts and services. The Textron Systems segment offers electronic systems and solutions, advanced marine craft, piston aircraft engines, and others. The Industrial segment designs and manufactures a variety of products within the Kautex and Specialized Vehicles product lines.
REASON FOR COMMENT
The following are key takeaways from Textron’s CFO David Rosenberg, at our 32nd Annual Aerospace & Defense Symposium:
How are you strategically repositioning yourself? The defining initiative of the year is the divestiture of the Industrial segment. Announced in April as new CEO Lisa Atherton’s first major action, the process contemplates 12 months for a direct sale or 18 months for a spin, with both paths run in parallel and the spin deliberately included so investors would believe the company intends to follow through after several failed attempts to sell Kautex over the past decade.
What is the MV-75 funding gap? Following last year’s reconciliation budget process, the Army elected to accelerate the MV-75 program, with Textron estimating approximately $600 million required in fiscal 2026; the first $300 million arrived in December, but the second tranche of roughly $350 million did not materialize as expected, and by July 1 multiple contract line items had exhausted funding. Textron elected to self-fund and continue the program.
What are your objectives with Textron Aviation? Management identified achieving 200 jets and 200 turboprops annually as the number one priority for capital and engineering allocation, quantifying the cost of current inefficiency, normalized for post-COVID manufacturing conditions, at roughly $150 million of annual profit. Critically, the plan does not contemplate increasing the engineering budget but reallocating it toward producibility.
What is the product pipeline & progress with MV-75? The first Citation Ascend, a derivative of the XLS, was delivered this year, with three Gen3 products following next year comprising the M2, CJ3, and CJ4, all featuring auto-land capability; the CJ4 is sold out for approximately three years. On the MV-75, the first two fuselages are finishing in Wichita and will ship to Amarillo for wing installation ahead of the first flight vehicle, alongside extensive ground testing, with publicly available Army commentary indicating roughly 60 aircraft per year at rate.
What are the aftermarket economics? Aftermarket represents roughly 33% of Textron Aviation revenue and a higher percentage of profit, growing 5-6% annually split roughly evenly between volume and price, tracking daily utilization data growing 2-3%. Management was direct that service centers exist to satisfy customers and sell aircraft, while the profit resides in parts, and described a dynamic pricing model introduced approximately six years ago for commodity aftermarket parts to compete in an e-commerce environment. On portfolio discipline, management emphasized that every business must justify itself, noting the Mustang, Sovereign, Citation Ten, and King Air C90 have all been discontinued where buyers would trade up into more profitable aircraft.
Unmanned Aerial Vehicle (UAV) Panel A&D Symposium Highlights
COMPANY OVERVIEW
The lunch panel brought together four suppliers to the uncrewed systems market alongside the industry’s trade association. Unusual Machines (UMAC) manufactures drone powertrain components; Lantronix (LTRX) supplies edge compute for onboard computer vision; Kopin (KOPN) produces microdisplays for drone operators and weapon sights; Hidden Level provides distributed passive radar and RF sensing as a data service; and AUVSI is the largest trade association representing uncrewed systems and autonomous technologies.
REASON FOR COMMENT
The following are key takeaways from UMAC’s CEO Allan Evans, Lantronix’s CEO Saleel Awsare, Kopin’s CEO Michael Murray, and Hidden Level’s Founder and CEO Jeff Cole, on a panel moderated by AUVSI’s President and CEO Michael Robbins, at our 32nd Annual Aerospace & Defense Symposium:
Policy as the Foundation of the Domestic Industry (AUVSI). Moderator Michael Robbins framed the session around a period of tremendous disruption, noting that recent world events have drawn far more policy attention to drones, autonomy, and counter-drone than ever before. The toolkit includes defensive measures such as Blue UAS and NDAA component requirements and FCC restrictions on foreign adversarial products, alongside offensive measures including Office of Strategic Capital loans and Industrial Base Analysis and Sustainment awards.
Onshoring Economics & Forward Buying (UMAC). Allan Evans was direct that the company would not exist without policy, since absent American component requirements Unusual Machines could not compete with DJI, and characterized the opportunity as a legislatively created market vacuum. The company grew eight times year over year and plans on the assumption, acknowledged as dangerous under normal conditions, that demand is effectively unlimited, ordering inputs roughly nine months forward including magnets from one of the only non-Chinese vendors.
Edge Compute Ramp & Autonomy Requirements (LTRX). Saleel Awsare noted drone revenue was near zero twelve months ago and crossed $12.5 million within a year, with management anticipating it doubling again. Lantronix is NDAA-certified with U.S. country of origin, which creates a unique opening as commercial and industrial buyers, including drone-as-first-responder programs, can no longer purchase DJI equipment.
Domestic Semiconductor Production & Workforce (KOPN). Michael Murray described receiving SAM-DIB and IBAS funding precisely because he declined a government request, having argued Kopin could not compete domestically against China’s micro-LED investment; the government responded by helping build a domestic production line. When management arrived four years ago, 80% of manufacturing including all design work was in China, and the pivot away was made in the third month over objections from investors, customers, and the board, driven by customers requiring U.S.-built displays because these are active components.
Distributed Sensing, Counter-Drone Authority (Hidden Level). Jeff Cole described a distributed sensing layer built on passive radar and precision RF geolocation, sold as infrastructure because customers want the data rather than the radars. The Safer Skies Act, included in the December NDAA, delegated counter-drone authority to state and local officials, materially improving buyer comfort by clarifying how a response can be executed.
As of June 30, 2026, affiliates of GAMCO Investors, Inc. beneficially owned 5.61% of of Ducommun, 2.98% of Graham Corporation, 2.41% of Astronics Class A and less than 1% of Class B, 2.37% of Moog Class A and less than 1% of Class B, 1.38% of Textron, and less than 1% of all other companies mentioned.
For investors seeking exposure to this evolving defense landscape, the Gabelli Commercial Aerospace and Defense ETF (GCAD) offers targeted access to companies developing the advanced capabilities that define modern military operations. GCAD focuses on defense technology companies at the intersection of building stealth aircraft, precision munitions, unmanned systems, and advanced sensors essential to maintaining strategic advantage in contested environments. As geopolitical tensions drive sustained defense spending and procurement modernization, GCAD provides a way to participate in the growth of the defense technology sector shaping military operations for decades to come.
Semper Fi,
LtCol Tony Bancroft, USMCR (Ret.)
Tbancroft@gabelli.com
914.921.5083
Important Disclosures
• Shares of this ETF are bought and sold at market price (not NAV) and are not individually redeemed from the fund.
• Buying or selling ETF shares may require additional fees such as brokerage commissions, which will reduce returns.
• These additional risks may be even greater in bad or uncertain market conditions.
You should consider the ETFs’ investment objectives, risks, charges and expenses carefully before you invest. The ETFs’ Prospectus and Summary Prospectus are available from G.distributors, LLC, a registered broker-dealer and FINRA member firm, and contains this and other information about the ETFs, and should be read carefully before investing. To obtain a Prospectus or Summary Prospectus, please call 800-GABELLI or visit https://www.gabelli.com/funds/etfs/documents.
Distributed by G.Distributors, LLC, a registered broker-dealer and FINRA member firm.